
Thinking about planting roots in North York? This corner of Toronto nails the mix of calm neighborhoods and city buzz. You’ve got quiet streets, alongside lively shopping spots. Sounds appealing, right? But wading into the real estate scene can feel like a lot. That’s where this guide comes in. We’re breaking down what’s happening with home prices and sorting through your mortgage choices. The goal? To hand you the knowledge to jump in with confidence.
North York as a Growing Real Estate Hub
North York isn’t just a suburb. It’s a mini-city all its own. Big companies line Yonge Street, and getting around is a breeze thanks to the 401, 404, and the subway. All that adds up to a real estate market that’s got its own energy.
What attracts investors and buyers to North York?
- A House for All: There is an enormous range, from contemporary condos near Yonge and Sheppard to opulent detached homes in areas like York Mills and The Bridle Path. You’re sure to find something that suits your taste and budget.
- Facilities Plenty: Imagine top-notch shopping (Yorkdale, Bayview Village), a mouthwatering culinary scene, and a plethora of cultural attractions. Simply put, living here translates into a superior quality of life.
- Investment Gold: Being in the center of the GTA and always improving its infrastructure means property values are likely to keep climbing. A smart place to invest and secure your future.
To make a confident move in this competitive market, it’s important to understand prices and financing. Let’s get into the details.
Current Housing Prices in North York
Like the rest of the GTA, North York’s real estate market sees prices change a lot based on the type of property, how big it is, and which neighbourhood it’s in. Keep in mind that the numbers below are averages, and what you actually pay can depend on the specific property and what’s going on in the market when you buy.
Average Home Prices (Approximate, as of Late 2024/Early 2025):
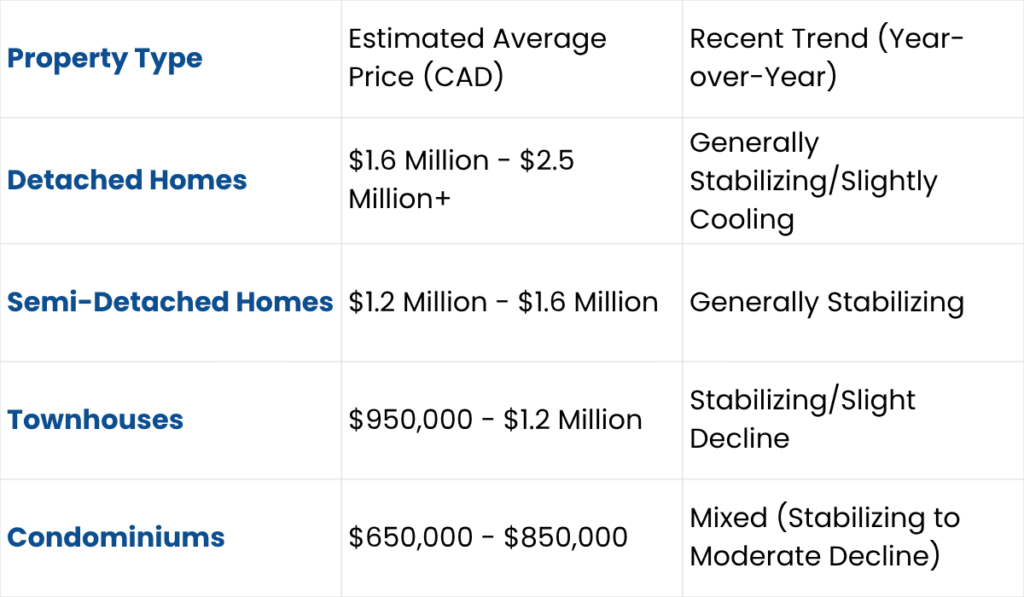
Remember: These are just rough estimates, and the wider Toronto market is either leveling out or cooling down a bit, with more homes available. Since the market’s always moving, talk to a real estate pro for the latest numbers.
What affects these prices the most? Three main things:
- Location, Location, Location: Areas with great schools, easy subway access, and nice extras – like Willowdale and Bayview Village, usually cost more. You’re paying for convenience and a high quality of life.
- Schools and Subway: Being near good schools or the subway helps homes hold their value, even when the market cools a little. A top-rated school can be a big selling point.
- Transit Links: Getting around easily makes a big difference. Living close to the Yonge-University subway or the future Finch West LRT pushes up prices, especially for condos and townhouses.
Real Estate Market Trends in North York
Right now, North York’s real estate scene is more balanced than before. That said, popular single-family homes still see a lot of action.
Inventory Levels: There are generally more listings now, especially for condos. That means buyers have more to choose from and face less pressure in bidding wars. Now’s the time to take your time and negotiate.
Underlying Demand: Don’t worry, there are still lots of people wanting to buy here! For instance:
- First-Timers: They often go for condos near the subway, using insured mortgages to make their dream of owning a home a reality. With those prices, it’s a must!
- Investors: They’re still interested in renting properties in busy areas like Yonge & Finch and Sheppard because rentals in Toronto are hard to find.
- Looking to Upgrade: They’re taking advantage of stable prices and more homes for sale in the detached and semi-detached markets to find something bigger and better.
Hot Neighbourhoods:
- Willowdale: Families and professionals love it here! You’ll find everything from old bungalows to new custom houses and sleek condos.
- Bayview Village: Known for its fancy homes, great shops, and family-friendly vibe. Expect to pay a premium.
- Downsview: This area is being renewed, offering some lower-priced options for getting into the North York market, mostly older townhouses and condos.
- Don Valley Village / Pleasant View: These are often mentioned as good options for those hoping to buy a condo for the first time in North York.
Mortgage Options for Homebuyers in North York
Getting your mortgage right is super important, especially in Toronto where things can be pricey.
A. Traditional Fixed-Rate and Variable-Rate Mortgages
- Fixed-Rate Mortgages: These keep your payments steady for a set time (usually 3-5 years). Good for budgeting, especially when rates are jumping around. If you are worried about the cost of your house going up, then this would be good for you.
- Variable-Rate Mortgages: The interest changes with the Bank of Canada’s prime rate. You might get a lower rate to start, but your payments could change.
Which one is better? It depends on how comfortable you are with risk and what you think interest rates will do.
B. CMHC-Insured Mortgages for First-Time Buyers
If you put less than 20% down, you’ll need mortgage default insurance, usually called Canada Mortgage and Housing Corporation (CMHC) insurance (though Sagen and Canada Guaranty offer it too). For many first-time buyers in North York, this is how they get their foot in the door for homeownership.
- The Rule: Put down at least 5% of the first $500,000, then 10% on what’s left up to $1.5 million.
- The Bonus: It makes buying a home possible sooner.
CMHC also has the Home Start program, which lets first-time buyers or those buying new homes spread their payments over 30 years. There’s a higher insurance fee, but it lowers your monthly expense and makes things more affordable.
Don’t forget to check out property tax and affordability trends in Toronto.
C. Jumbo Mortgages for High-Value Homes
The fancy areas of North York have homes that need bigger mortgages than usual. Canada doesn’t officially call them “jumbo mortgages” like in the US, but lenders have special deals for properties over $1.5 million.
- The Catch: You’ll need at least 20% down, a credit score of 700 or higher, a low debt-to-income ratio, and lots of cash saved up.
- The Perk: You can buy those high-end homes in places like The Bridle Path, York Mills, and Bayview Village.
D. Private Lenders and Alternative Financing
If you have complicated income, credit problems, or need a short-term loan, private lenders are an option.
- Compared to Banks: They’re more flexible with who they lend to, but charge higher interest and fees. They’re often a temporary fix, not a long-term solution.
Home Affordability and Buyer Considerations in North York
How affordable is North York? It comes down to two big things: how much money you make and what mortgage rates are doing.
- Income and the Stress Test: Here’s the deal: to get a mortgage in Canada, you need to pass the “stress test.” That means proving you can handle a rate that’s 2% higher than what you’re actually paying, or the Bank of Canada’s rate (currently 5.25%) – whichever is higher. This affects how much you can borrow. Make sure that the pre-approval with your bank is done with verified income documentation instead of taking the sales pitch at face value
- Down Payment Requirements: Toronto has high prices, so here’s what you need to put down:
- 5% on the first $500,000
- 5% of the first $500,000 and 10% on the rest up to $1,500,000
- 20% on homes over $1.5 million (uninsured mortgage).
Closing Costs For Buying A House In Ontario: Don’t forget to budget for closing costs! They’re usually 1.5% to 4.0% of the purchase price, plus rebates. The main costs are:
- Ontario Land Transfer Tax (LTT): A tax from the province on all property sales.
- Toronto Municipal Land Transfer Tax (MLTT): Since North York is part of Toronto, you pay both the provincial and city tax.
- First-Time Buyer Rebates: If you’re a first-time buyer, you can get some money back: up to $4,000 on the Ontario LTT and $4,475 on the Toronto MLTT.
Tips for Buyers in North York
- Think Timing, but Mainly, Just Be Ready: Instead of waiting for the perfect moment, focus on when you’re ready and have your finances in order. If things have calmed down a bit, you can find good deals by looking for homes that have been on the market for a while.
- Mortgage Brokers vs. Banks:
- Brokers: They work with lots of different lenders (banks, credit unions, private lenders), so they can find the best rate and mortgage for you, even if your situation is complicated.
- Banks: It’s simpler to go straight to a bank, but they can only offer you their own products.
- Long-Term Thinking: North York keeps growing, has great transit, and a strong rental market, making it a solid investment for the future. Try to live close to the subway for even better value over time.
The North York real estate market is tricky, but it can be worth it. Prices are high, sure, but there are more homes available and lots of mortgage options North York buyers can explore. Success means getting informed, planning your finances, and working with pros. Also, check out our Step-by-Step Guide to Buying a House in Canada for details on the buying process.
Don’t go it alone! Connect with a mortgage advisor and real estate professional today for personalized market data and top financing strategies for buying a house in North York.
Frequently Asked Questions (FAQs)
- What is the average price of a home in North York?
As of late 2024/early 2025, condo prices range from about $650K to $850K. Detached homes? Think $1.6 million to over $2.5 million.
- Are condo prices climbing faster than house prices around here?
Not right now. Condo prices are pretty stable or even dropping a bit, while houses stay steady, but at a much higher price. It really depends on which street and building you’re looking at.
- What kind of mortgages can first-time buyers get in North York?
Look into CMHC-insured mortgages; they let you put as little as 5% down. You can pick between a fixed or variable rate.
- Can I get a huge mortgage for a fancy home in North York?
Yep! Banks offer special financing for homes above $1.5 million. Expect to need at least 20% down, good credit, and some savings.
- How are private lenders different from banks when it comes to getting a mortgage in North York?
Private lenders are easier to qualify with, but they’ll charge you higher interest and fees.
- What’s the bare minimum I need for a down payment to buy in North York?
Here’s the breakdown:
- 5% of the purchase price for homes $500,000 or less.
- 5% of the first $500,000 of the purchase price, plus 10% for the portion of the purchase price above $500,000 (up to $1.5 million, as new rules have extended the cap for insured mortgages).
- 20% of the purchase price for homes $1,500,000 or more.
- Do mortgage rates in North York differ from other Toronto neighbourhoods?
A: Nope, rates are set by the lender and depend on the overall economy, not where you live in the city.
- How much do closing costs impact the price?
Closing costs, including those land transfer taxes, can add up to 2-4% of the purchase price. That’s a significant chunk of cash you’ll need upfront.
- Which North York neighbourhoods are easiest on the wallet for buyers?
Check out Downsview and Don Valley Village. They tend to have more condos and older townhouses, which are more affordable.
- Will a home in North York pay off in the long run?
Historically, yes. North York’s location, transit, and strong economy usually mean properties hold their value well.


